Use your Super to invest in property.
For some Australians, a Self-Managed Super Fund (SMSF) offers a way to take control and invest in residential property if it’s structured right.
Using SMSF to build your property portfolio
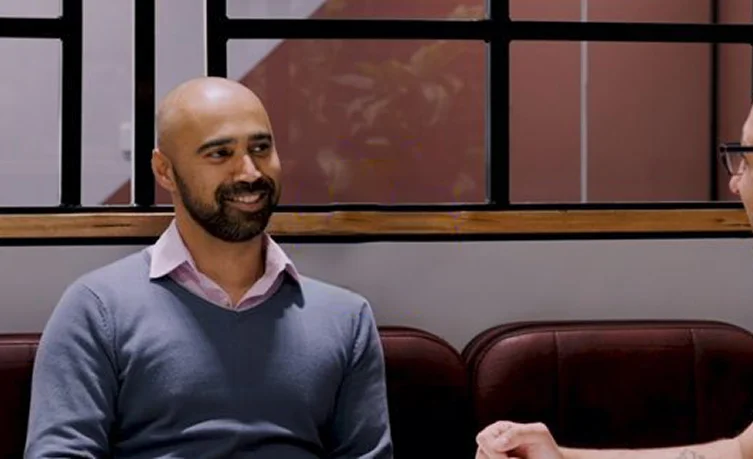
In this video
Kiran Khan, OpenCorp Senior Property Strategist, talks through what you need to know about when considering using your SMSF to build your property portfolio.
SMSF property investment, done the right way
Investing through an SMSF offers flexibility but it also comes with specific rules and responsibilities.
Here’s how we help:
Understand what’s possible under SMSF rules
We’ll help you make sense of ATO requirements and explain how SMSF lending works in plain language.

Get the structure right from the start
From deposits and loan types to Limited Recourse Borrowing Arrangements (LRBAs), we support the setup process alongside your licensed professionals.
Work with your licensed financial adviser
We do not provide financial advice, but we coordinate with your adviser to ensure everything aligns with your retirement strategy.
Stay compliant every step of the way
We guide the lending and property piece, so your SMSF stays within the boundaries of what’s allowed. If you need advice on whether an SMSF strategy suits you, we can help you find a licensed specialist that understands SMSF property investment.
Not sure if property fits in your Super?
It’s not about rushing in, it’s about knowing what’s possible and being supported by the right experts.
Learn what’s involved
From property eligibility to the responsibilities of trustees borrowing money, we’ll explain the practical steps.
Know the risks before you proceed
SMSF property investing isn’t suitable for everyone. That’s why we ensure independent licensed advice is obtained before any decisions are made.
A lending process designed for SMSFs
We explain lending limits, loan structures and compliance requirements all before you move forward.
Support aligned with long-term goals
We help ensure your property investment strategy aligns with both SMSF rules and your broader retirement objectives.
The SMSF property investment process
We support you through the entire process. From initial enquiry to settlement and beyond.
Book your discovery call
We understand your property goals and our finance brokers provide general guidance on how SMSF lending works.
Assess your fund’s readiness
We help determine whether SMSF lending might be viable based on asset levels and contribution capacity.
Speak to a licensed SMSF adviser (if req)
If you haven’t already done so, we’ll help you connect with an independent licensed professional to help assess suitability and provide personal advice.
Create your property strategy
Once advice is in place, we help structure the loan and property purchase in line with SMSF rules.
Secure compliant lending
We structure your loan under LRBA guidelines and ensure all lender requirements are met.
Find the right property
We use our proven process to source a property that aligns with SMSF investment rules and your long-term goals.
Support through to settlement & beyond
We coordinate with your fund administrator and ensure everything remains compliant through to settlement and beyond.
SMSF property investing FAQs
Can I use my Super to invest in property?
Yes, under certain conditions. The ATO allows SMSFs to acquire property if it meets specific criteria around investment purpose, structure, and borrowing limits.
Can I live in the property or rent it to family?
No. SMSF-acquired property must be held purely for investment purposes and cannot be occupied or leased by fund members or related parties (ATO rule).
Does OpenCorp provide financial advice?
No. We do not provide financial product advice, taxation advice, or legal advice. We support the property and lending process and refer you to a licensed financial adviser where appropriate.
How much Super do I need to get started?
Generally, lenders require your SMSF to hold $200,000+ in assets. Your adviser will confirm if property is appropriate based on your fund’s structure.
What’s an LRBA?
A Limited Recourse Borrowing Arrangement (LRBA) allows your SMSF to borrow to acquire a property, while ensuring other fund and personal assets are protected in case of loan default.
What are the risks?
Like any investment, there are risks. Such as vacancy, compliance breaches, or liquidity issues. That’s why licensed financial advice and expert property and finance guidance is essential.
You’ve worked hard for your Super. Let’s make it work for you.
If property investing through your SMSF fits your long-term goals, we’ll help you move forward with clarity, structure and full compliance.
Form / Strategy Session / Landing
"*" indicates required fields
Disclaimer
OpenCorp does not provide financial product advice, taxation advice, or legal advice. This content is general in nature and does not consider your objectives, financial situation, or needs. Before acting on any information about SMSFs or property investment, you must obtain advice from a licensed financial adviser, accountant, or tax professional.
Nothing on this page constitutes an offer to acquire a financial product or establish an SMSF. SMSF lending must comply with ATO regulations and involves strict structural requirements. For more information, visit ato.gov.au.